Global Semiconductor IP Market- Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning / Landscape Review & Global Market Size Forecast to 2034

8.3%
CAGR (2026-2034)
7.59 USD Bn.
Forecast Market Size
316
Report Pages
157
Market Tables

Overview

Semiconductor Intellectual Property Market size was valued at USD 7.59 Billion in 2025 and the total Semiconductor Intellectual Property revenue is expected to grow at a CAGR of 8.3% from 2026 to 2034, reaching nearly USD 15.55 Billion by 2034.

Semiconductor Intellectual Property Market Overview

Semiconductor IP refers to a piece of design that is a reusable unit of logic or functionality or a layout of a design that is developed with the idea of licensing it to many vendors for using it as a building block in different chip designs. Semiconductor IP helps to provide integrated circuit layout design that is the intellectual property of its creator or party.

1.According to an estimate, about 5 billion people around the world have access to the internet every day, and about 65% use laptops. By the end of 2025, global laptop shipments are projected to reach 270 million units.

2. According to MMR analysis, the average American has access to 10 or more connected devices in their home that are semiconductor-enabled.

The semiconductor intellectual property market is poised for significant growth between 2025 and 2034 driven by a mix of factors that offer promising opportunities. The report offers a comprehensive analysis of the sector, providing in-depth insights into market divisions based on design, IP core, revenue source, application, and geographical region.

Semiconductor Intellectual Property Market Growth Outlook
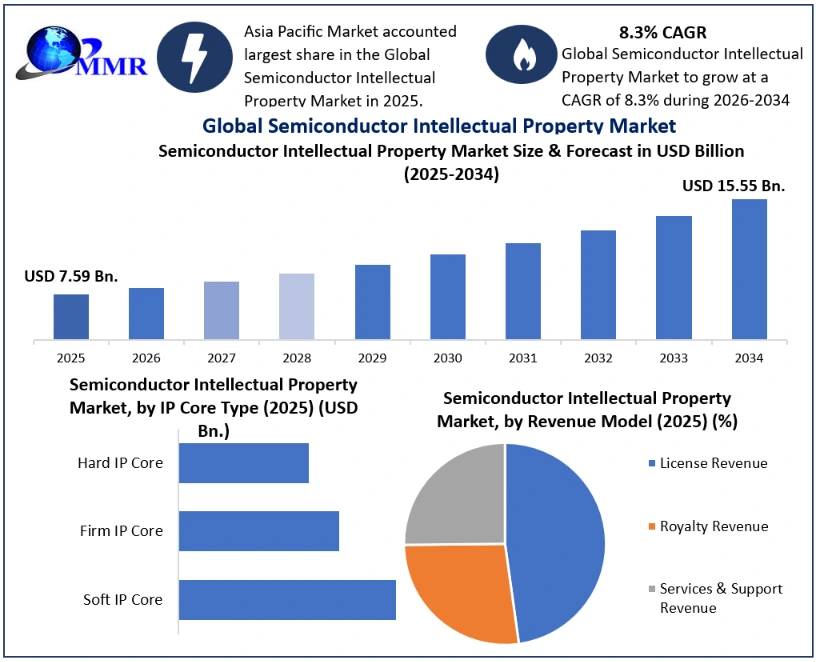
Semiconductor Intellectual Property Market Growth

To know about the Research Methodology :- Request Free Sample Report

The demand & integration of power electronics in consumer electronics and connected devices such as TVs, smartphones, wearable, connected vehicles, and others are driving the growth of semiconductor IP across the globe. Additionally, efficient, faster, and reliable processors, memory, and interface products further intensify the semiconductor intellectual property market demand in the future.

The advancements in multicore technology for consumer electronics and increasing demand for modern system-on-chip (soc) designs contribute to the market's upward trajectory. As consumers prioritize products with efficient and reliable processors, the market is expected to thrive. This scenario provides a fertile ground for established companies and new entrants to capitalize on emerging trends and favorable market dynamics.

Through meticulous research, the report reveals crucial information such as market size, share, growth trajectory, competitive framework, and key factors that drive or hinder market growth. This complete perspective of the Global Semiconductor intellectual property market assists stakeholders in identifying growth opportunities within the industry and making well-informed decisions.

1. In March 2023, India and the U.S. signed a memorandum of understanding (MoU) establishing the semiconductor supply chain and innovation partnership under the framework of India-U.S. Commercial Dialog.

Semiconductor Intellectual Property Market Dynamics

Healthcare Device Innovation Fuels Global Semiconductor IP Growth

The notable shift from large expensive traditional procedures to small, disposable, and minimally invasive therapeutic tools drives the semiconductor intellectual property market. These cutting-edge devices utilize microelectronic and micromechanical technologies which require precise and efficient manufacturing processes enabled by semiconductor IPs. The transformation in medical device technology regarding enhanced performance drives the demand for the semiconductor intellectual property market. The continuous evolution of diagnostic equipment like MRI, CT scans, and X-ray machines which depend on the semiconductor components to ensure precise imaging and accurate diagnosis necessitates the demand for high-quality semiconductor IPs. Additionally, the development of implantable medical devices including pacemakers, defibrillators, neurotransmitters, and drug delivery systems, etc., requires highly reliable electronic components manufactured using advanced semiconductor technologies contributing to the rising demand for semiconductor Intellectual property market growth.

The demand for semiconductor IP is on the rise as minimally invasive surgical procedures and wearable medical devices like endoscopes, surgical robots, etc rely on advanced electronic components. INFORMED, a European initiative that increases innovation in microfabricated medical devices by providing an integrated pilot production platform further fuels the demand for semiconductor IP components. For instance, Irish and Dutch partners of INFORMED have demonstrated innovations like smart dressings with integrated sensors, showcasing the potential of microfabricated medical devices in improving patient care. The advancements in medical device technology fueling innovation in diagnostic equipment, imaging devices, and implantable medical devices drive the demand for the semiconductor intellectual property market. As medical devices continue to evolve, the demand for semiconductor IP is positioned to remain tough, positioning the global semiconductor intellectual property market for significant growth.

1. According to MMR analysis, in 2022, about 200000 pacemakers have been implanted in the United States annually

Constant Advances in Technology resulting in an Increased Expenditure

As industries such as healthcare, automotive, and telecommunication grow, the need for semiconductor IPs rises but the cost of research and development, production, and implementation of advanced technologies puts pressure on the market players. The complexity of new IPs including advanced design techniques and cutting-edge manufacturing processes, demands sizeable financial investment from the companies. Though countries like Germany & France have strong industrial bases, the expenses of keeping up with rapidly advancing IP developments affect their market positioning. The innovation trends indicate the rise in semiconductor IP expenses owing to the need for miniaturization and high-performance semiconductor devices. For instance, the global semiconductor market is expected to grow at a CAGR of 6.3% from 2021 to 2026, but the increasing cost of R&D and production limits the semiconductor intellectual property market's growth potential. While constant advances in technology drive innovation in the global semiconductor intellectual property market, the resulting increase in expenditure presents a notable restraint.

Semiconductor Intellectual Property Market Segment Analysis

Based on IP Type, the Processor IP segment held the largest market share in the global Semiconductor Intellectual Property Market. According to MMR analysis, the segment is further expected to grow at a CAGR of 8.3% during the forecast period and stands out as the dominant segment within the Global Semiconductor Intellectual Property Market. Processor IPs are widely used in manufacturing consumer electronics like smartphones, tablets, CPUs, etc. and the constant demand of these electronics necessitates the need for advanced processor design. The rising sales of these smart IoT devices benefit the processor IPs segment growth in the global semiconductor intellectual property market. Additionally, AI & 5G technology requires processors that handle complex algorithms and vast amounts of data. An increase in speed, bandwidth, and data output for automotive & mobile applications has increased the complexity of infrastructure and application processor technologies and requires new processor IPs driving their demand in the global semiconductor intellectual property market.

1. According to MMR, the consumer's Internet of Things device sales are expected to increase from USD 45 billion in 2021 to USD 154 billion by 2028.


Processor IPs offer pre-designed and verified processor cores, enabling the designers to integrate processing functionality into their system on chips at lower costs, a crucial aspect for the key players to stay competitive in the fast-growing electronics market. The availability of a wide range of processors catering to different requirements provides a greater market further fueling the demand for processor IPs segment on the global semiconductor intellectual property market. As the electronics industry evolves, the demand for processor IP solutions is expected to grow with pace.

Semiconductor Intellectual Property Market Regional Insights

Asia Pacific dominated the Global Semiconductor Intellectual Property Market with the highest share in 2025 and is expected to grow at a CAGR of 8.3% during the forecast period and maintain its dominance during the forecast period. The dominance of the region is driven by considerable investments from the key players in electronic device manufacturing.

1. Samsung Electronics has planned to invest about USD 489 Billion in semiconductors and biologics in the next five years in the Asia Pacific region.

The presence of a large number of semiconductor manufacturing companies in the region, increasing demand for semiconductor IP solutions in industries such as consumer electronics and automotive, and the rising demand for semiconductor solutions in emerging technologies like IoT and wearable devices drives the demand for Semiconductor Intellectual Property Market in the region. The surge in digital products like laptops, tablets, and smartphones post-pandemic has been responsible for the growth of the semiconductor intellectual property market in the region as semiconductor IP chips are used in the core circuits. Countries like China, India, and Japan play a major role in consumer electronics device exports accounting for about 50% of the total exports in the region.

1. According to MMR analysis, the sales penetration of 5G-enabled smartphones in India reached 51% in the beginning of 2022, further accelerating the requirement of semiconductor IP chips.

Semiconductor Intellectual Property (IP) Market

Additionally, the automotive industry in India which contributes about 7.1% of the GDP is expected to become the third largest globally by 2034. The dependence of the automotive segment on semiconductor chips necessitates the development of new production design solutions in the region further fuelling the demand for Semiconductor Intellectual Property Market.

1. According to MMR analysis, Asia Pacific is the largest market for semiconductors globally with over 60% of global sales of which China accounted for about 30%.

Semiconductor Intellectual Property Market Competitive Landscapes

The Global Semiconductor Intellectual Property Market is competitive among companies owing to the presence of numerous players across the industry. The major players in the market include Arm Limited (UK), Synopsys, Inc. (US), Cadence Design Systems, Inc. (US), Imagination Technologies(UK), CEVA, Inc. (US), Lattice Semiconductor (US), Rambus (US), eMemory Technology Inc. (Taiwan), VeriSilicon (China), Achronix Semiconductor Corporation (US), among others. These companies are pushing boundaries, investing in research and development to expand their product lines, and undertaking strategic activities including new product launches, contractual agreements, mergers and acquisitions, and collaborations with other organizations. The Semiconductor Intellectual Property Market is growing significantly in the coming years owing to the rising trend of health wearables, increased use of laptops & tablets, and rising government support.

Arm Holdings plc, Synopsys, Inc., and Cadence Design Systems, Inc. maintain strong competitive positions through broad IP portfolios and established semiconductor design ecosystems. Arm focuses on processor architecture and compute IP, while Synopsys and Cadence offer interface, memory, verification, and foundation IP solutions. Rambus Inc. competes in memory and high-speed interface technologies, whereas Imagination Technologies specializes in graphics and compute IP.Other important participants, including CEVA, Inc., SiFive, Inc., Andes Technology Corporation, eMemory Technology Inc., VeriSilicon Microelectronics, Arteris, Inc., Faraday Technology Corporation, and Achronix Semiconductor Corporation, strengthen the market through specialized processor, connectivity, memory, RISC-V, and interconnect IP solutions. Increasing demand for AI processors, automotive semiconductors, IoT devices, chiplet architectures, and high-performance computing is encouraging companies to expand their IP portfolios, develop advanced design technologies, and establish strategic partnerships.

Semiconductor Intellectual Property Market Recent Industry Developments

Date Company Development Impact
04 March 2026 Various Industry Leaders The industry accelerated adoption of RISC-V architecture and chiplet-based designs to meet surging AI and 5G demand. This shift enhances scalability and reduces reliance on proprietary architectures, fueling 9.7% CAGR growth.
01 May 2025 Silvaco The company launched a strategic initiative to market, license, and provide support for Samsung Foundry’s advanced semiconductor design IP. This partnership expands access to high-performance silicon, shortening time-to-market for SoC designers.
01 May 2025 Quadric Quadric entered into a formal partnership with MegaChips to integrate advanced AI processing IP. The collaboration accelerates the deployment of edge computing capabilities in complex automotive SoCs.
01 August 2025 NVIDIA The company officially adopted a new, high-efficiency die-to-die connection protocol for its next-generation silicon. This protocol drives interface IP demand by enabling faster data transfer between chiplets in AI data centers.

Global Semiconductor IP Market Scope: Inquire before buying

Global Semiconductor IP Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: US $ 7.59 Bn.
Forecast Period 2026 to 2034 CAGR: 8.3% Market Size in 2034: US $ 15.55 Bn.
Segments Covered: by IP Type Processor IP
  CPU IP
  GPU IP
  DSP IP
  AI/NPU IP
Microcontroller IP
Memory IP
Interface IP
Analog & Mixed-Signal IP
Security IP
Others
by IP Core Type Soft IP Core
Firm IP Core
Hard IP Core
by Revenue Model License Revenue
Royalty Revenue
Services & Support Revenue
by Semiconductor Device Type Microprocessors
Microcontrollers
GPUs & Graphics Processors
AI Accelerators / NPUs
Connectivity & Networking ICs
Application-Specific ICs
Programmable Logic Devices
Others
by Revenue Source Consumer Electronics
Automotive
Telecommunications
Data Centers & Cloud Computing
Industrial
Healthcare
Aerospace & Defense
Others

Global Semiconductor IP Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Semiconductor Intellectual Property Market Key Players

North America
1. Synopsys, Inc.
2. Cadence Design Systems, Inc.
3. Rambus Inc.
4. CEVA, Inc.
5. Lattice Semiconductor Corporation
6. Silicon Image (Lattice Semiconductor Corporation — acquired 2015)
7. Silicon Storage Technology, Inc. (Microchip Technology Inc.)
8. Microchip Technology Inc.
9. Achronix Semiconductor Corporation
10. Analog Bits, Inc.
11. Arteris, Inc.
12. Eureka Technology, Inc.
13. Open Five, Inc.
14. Silvaco, Inc.
15. CAST, Inc.
16. Avery Design Systems, Inc.
17. Nvidia Corporation
18. Qualcomm Incorporated
19. Intel Corporation
20. Altera Corporation (Silver Lake / Intel Corporation — majority stake since 2025 spin-off)
21. Advanced Micro Devices, Inc. (AMD)
22. Xilinx, Inc. (Advanced Micro Devices, Inc. — acquired 2022)
23. Siemens EDA (Siemens AG — formerly Mentor Graphics, acquired 2017)
24. Broadcom Inc.
25. SiFive, Inc.
Others

Europe
26. Arm Holdings plc (SoftBank Group Corp. — majority shareholder)
27. Imagination Technologies Group plc (Canyon Bridge Capital Partners)
28. Alphawave IP Group plc (Alphawave Semi)
29.Cobham Gaisler AB (Cobham Limited)
30. Dolphin Design SAS
31.Dream Chip Technologies GmbH
32. TES Electronic Solutions GmbH
33. TransPacket AS
Others

Asia Pacific
34. eMemory Technology, Inc.
35. VeriSilicon Microelectronics Co., Ltd. (VeriSilicon Holdings Co., Ltd.)
36. Faraday Technology Corporation
37. M31 Technology Corporation
38. Andes Technology Corporation
39. Renesas Electronics Corporation
40. Fujitsu Limited
41. Digital Media Professionals Inc. (DMP)
42. TAKUMI Corporation
Others

Frequently Asked Questions:

1. What are the growth drivers for the Semiconductor Intellectual Property Market?
Ans. Growing Adoption of Connected Devices for Daily Use and Increasing Demand for Electronics in Healthcare and Telecommunications Industries fuels the Semiconductor Intellectual Property Market growth.

2. What are the trends in Semiconductor Intellectual Property Market growth?
Ans. The rising popularity of Risc-V Processor Technology and increasing AI, IoT, and other technologies are the trends in for Semiconductor Intellectual Property Market.

3. Why do consumer electronics have the largest market share in the Semiconductor Intellectual Property Market?
Ans. Consumer electronics, such as smartphones, tablets, and smartwatches, drive the demand for high-performance semiconductors due to their evolving functionalities and increasing popularity among consumers, leading to a significant market share in the industry.

4. What is the projected market size & and growth rate of the Semiconductor Intellectual Property Market?
Ans. Semiconductor Intellectual Property Market size was valued at USD 7.59 Billion in 2025 and the total Semiconductor Intellectual Property revenue is expected to grow at a CAGR of 8.3% from 2026 to 2034, reaching nearly USD 15.55 Billion by 2034.

5. What segments are covered in the Semiconductor Intellectual Property Market report?
Ans. The segments covered in the Semiconductor Intellectual Property Market report are design, IP core, revenue source, industry, and region.

Table of Contents

1. SECTION A – GLOBAL SEMICONDUCTOR INTELLECTUAL PROPERTY MARKET INTRODUCTION 1.1 Executive Market Landscape and Industry Overview 1.1.1 Global Semiconductor Intellectual Property Market Size (Value USD Mn), 2025–2034 1.1.2 Historical Market Size Trends and Growth Momentum Analysis Across Semiconductor IP Industry 1.1.3 Forecast Revenue Projections with Underlying Market Growth Driving Factors 1.1.4 Increasing Chip Design Complexity and Its Impact on Semiconductor IP Demand 1.1.5 Growth of Fabless Semiconductor Companies Supporting IP Adoption 1.1.6 Increasing System-on-Chip Integration and Reusable IP Requirements 1.1.7 Demand-Supply Dynamics Across Semiconductor IP Providers and Chip Designers 1.1.8 CAGR Analysis of Global Semiconductor Intellectual Property Market (2025–2034) 1.2 Semiconductor Intellectual Property Market Dynamics 1.2.1 Semiconductor Intellectual Property Market Trends 1.2.2 Semiconductor Intellectual Property Market Dynamics 1.2.3 Drivers 1.2.4 Restraints 1.2.5 Opportunities 1.2.6 Challenges 1.2.7 PORTER’s Five Forces Analysis 1.2.8 PESTLE Analysis 1.3 Semiconductor IP Pricing Structure and Value Chain Profitability Assessment 1.3.1 Comprehensive Breakdown of Semiconductor IP Licensing Cost Structure 1.3.2 Royalty-Based and Fixed-Fee Semiconductor IP Licensing Models 1.3.3 Margin Distribution Among IP Vendors, EDA Companies, and Chip Designers 1.3.4 Impact of IP Complexity and Technology Node on Licensing Fees 1.3.5 Influence of Customization and Design Support on IP Pricing 1.3.6 Recurring Revenue Models Across Semiconductor IP Providers 1.3.7 Impact of IP Reusability on Chip Design Economics 1.4 Semiconductor IP Developer Ecosystem and Supplier Dynamics 1.4.1 Global Semiconductor IP Developer Ecosystem Overview 1.4.2 Leading Semiconductor IP Developers and Technology Portfolios 1.4.3 Fabless Semiconductor Companies and IP Developer Demand Dynamics 1.4.4 Integrated Device Manufacturers and Internal IP Development Strategies 1.4.5 Design House and ASIC Design Service Provider Ecosystem 1.4.6 EDA Tool Providers and Semiconductor IP Developer Integration 1.4.7 IP Developer–Foundry Collaboration Models 1.4.8 Third-Party IP Developers and Technology Licensing Models 1.5 Chip Design Complexity and Semiconductor IP Demand 1.5.1 Increasing SoC Complexity Driving Third-Party IP Adoption 1.5.2 Advanced Node Design Challenges and IP Requirements 1.5.3 Chiplet Architecture and Modular IP Integration Trends 1.5.4 Heterogeneous Computing Supporting Specialized IP Demand 1.5.5 Multi-Core and Many-Core Processor Design Trends 1.5.6 Increasing Functional Integration Across Consumer and Computing Chips 1.5.7 Custom Silicon Development and Application-Specific Chip Design Growth 1.6 Semiconductor IP Technology Evolution and Design Innovation 1.6.1 Development of Advanced Processor and CPU IP Cores 1.6.2 GPU and AI Accelerator IP Development 1.6.3 DSP and Specialized Processing IP Evolution 1.6.4 High-Speed Interface and Connectivity IP Development 1.6.5 Memory Controller and Memory Interface IP Innovation 1.6.6 Security IP and Hardware Root-of-Trust Development 1.6.7 Chiplet and Die-to-Die Interconnect IP Evolution 1.7 Advanced Chip Design, AI, and Next-Generation Semiconductor Architecture 1.7.1 Rising Demand for AI and Machine Learning Accelerator IP 1.7.2 Generative AI Hardware and Specialized Chip Design Requirements 1.7.3 RISC-V Architecture Adoption Across Semiconductor Design 1.7.4 ARM-Based Processor IP Demand Across Application Markets 1.7.5 Chiplet-Based Architecture and Modular Chip Design Development 1.7.6 3D IC and Advanced Packaging Design Requirements 1.7.7 Hardware Acceleration and Domain-Specific Architecture Development 1.7.8 Neuromorphic and Emerging Computing Architecture IP Opportunities 1.8 Semiconductor IP Verification, Validation, and Design Quality Dynamics 1.8.1 Growing Importance of IP Verification Across Advanced Chip Designs 1.8.2 Functional Verification and Design Validation Requirements 1.8.3 Pre-Silicon Verification and Simulation Technologies 1.8.4 Formal Verification and Hardware Validation Adoption 1.8.5 Design-for-Test IP and Built-In Self-Test Technologies 1.8.6 Verification Reuse Across Multiple Semiconductor Designs 1.8.7 Third-Party IP Quality and Reliability Assessment 1.9 EDA Integration and Semiconductor Chip Design Workflow 1.9.1 Integration of Semiconductor IP With EDA Design Platforms 1.9.2 Electronic Design Automation Tools Supporting IP Development 1.9.3 RTL Design and IP Integration Workflows 1.9.4 Synthesis and Physical Design Integration 1.9.5 Simulation and Verification Tool Adoption 1.9.6 AI-Assisted Electronic Design Automation Technologies 1.9.7 Cloud-Based Semiconductor Design and EDA Platforms 1.9.8 Digital Design Automation Supporting Faster Chip Development 1.10 Digital Transformation and AI-Enabled Semiconductor Design Technologies 1.10.1 Artificial Intelligence Applications Across Semiconductor Chip Design 1.10.2 Machine Learning for Design Optimization and Verification 1.10.3 Generative AI Applications in RTL and Hardware Design 1.10.4 AI-Based Electronic Design Automation Platforms 1.10.5 Automated IP Selection and Design Reuse Technologies 1.10.6 Digital Twin Applications Across Semiconductor Design Processes 1.10.7 Cloud-Based Collaborative Chip Design Environments 1.11 Semiconductor Security, Functional Safety, and Compliance Dynamics 1.11.1 Growing Demand for Hardware Security IP 1.11.2 Hardware Root-of-Trust and Secure Boot Technologies 1.11.3 Cryptographic IP and Encryption Accelerator Development 1.11.4 Security IP for Automotive and Industrial Semiconductor Applications 1.11.5 Functional Safety Requirements for Automotive Chip Designs 1.11.6 Hardware Security Requirements for IoT and Connected Devices 1.11.7 Trusted Semiconductor Supply Chain and IP Security Requirements 1.12 Semiconductor IP Licensing and Contractual Business Model Analysis 1.12.1 Global Semiconductor IP Licensing Trends 1.12.2 Fixed-Fee IP Licensing Models 1.12.3 Royalty-Based Licensing Structures 1.12.4 Subscription and Recurring IP Licensing Models 1.12.5 Per-Design and Per-Unit Licensing Arrangements 1.12.6 Cross-Licensing and Strategic IP Partnership Models 1.12.7 IP Customization and Engineering Service Agreements 1.13 Semiconductor IP Procurement and Chip Designer–IP Developer Relationship Dynamics 1.13.1 IP Selection Criteria Among Semiconductor Chip Designers 1.13.2 Technology Compatibility and Performance Influence on IP Developer Selection 1.13.3 IP Developer Evaluation Based on Reliability and Verification Quality 1.13.4 Long-Term IP Licensing and Developer Partnership Agreements 1.13.5 Technical Support and Design Integration Services 1.13.6 Customization and Co-Development Models 1.13.7 IP Portability Across Semiconductor Process Nodes 1.14 Investment Trends and Capital Allocation Analysis 1.14.1 Investment Trends Across Semiconductor IP Providers 1.14.2 R&D Investment in Advanced Chip Design Technologies 1.14.3 Capital Allocation Toward AI and Accelerator IP Development 1.14.4 Investment in Chiplet and Advanced Packaging IP 1.14.5 Investment in RISC-V and Open Architecture Development 1.14.6 Strategic Investment in Regional Semiconductor Design Ecosystems 1.14.7 Mergers and Acquisitions Across Semiconductor IP and EDA Industries 1.15 Strategic Risk Assessment 1.15.1 Intellectual Property Protection and Licensing Risks 1.15.2 High R&D Costs Affecting Semiconductor IP Development 1.15.3 Advanced Node Complexity Increasing IP Development Costs 1.15.4 IP Integration and Compatibility Risks Across Chip Designs 1.15.5 Design Verification Challenges Affecting Time-to-Market 1.15.6 Dependence on Major Foundries and EDA Ecosystems 1.15.7 Geopolitical Restrictions Affecting Semiconductor Technology and IP Transfers 1.16 Semiconductor IP Lifecycle and Design Reuse Analysis 1.16.1 Semiconductor IP Development Lifecycle from Concept to Deployment 1.16.2 IP Architecture Development and RTL Design Stages 1.16.3 Verification and Qualification of Semiconductor IP 1.16.4 IP Integration Across Multiple Chip Designs 1.16.5 IP Reuse Across Process Nodes and Product Generations 1.16.6 IP Portability and Technology Migration Requirements 1.16.7 IP Maintenance, Updates, and Version Management 1.17 Semiconductor Design Cycle and Demand Performance Analysis 1.17.1 Chip Design Cycles and Their Influence on IP Demand 1.17.2 Seasonal Variation in Semiconductor Design Activity 1.17.3 Product Launch Cycles Affecting IP Procurement 1.17.4 Foundry Technology Roadmap Influence on IP Development 1.17.5 New Process Node Introduction and IP Qualification Cycles 1.17.6 AI and Computing Product Development Cycles 1.17.7 Design Pipeline Visibility Across Major Semiconductor Companies 1.18 Regulatory Framework, Standards, and Compliance Analysis 1.18.1 Global Semiconductor IP Protection and Licensing Regulations 1.18.2 Intellectual Property Rights and Semiconductor Design Protection 1.18.3 Export Controls Affecting Semiconductor Design Technologies 1.18.4 Technology Transfer Restrictions Across Major Semiconductor Markets 1.18.5 Automotive Functional Safety Standards Influencing Chip Design 1.18.6 Hardware Security Standards and Compliance Requirements 1.18.7 Open-Source Hardware Licensing and RISC-V Ecosystem Regulations 1.19 Semiconductor IP Ecosystem Partnerships and Strategic Collaboration Analysis 1.19.1 Strategic Partnerships Between IP Vendors and Chip Designers 1.19.2 IP Vendor–Foundry Collaboration Models 1.19.3 EDA–IP Vendor Integration Partnerships 1.19.4 Semiconductor IP Co-Development Programs 1.19.5 University and Research Institution Collaboration 1.19.6 Open-Source Hardware and RISC-V Ecosystem Development 1.19.7 Strategic Alliances Supporting AI and Accelerator Chip Design 1.20 Emerging Chip Design Architectures and Semiconductor IP Demand Analysis 1.20.1 Chiplet-Based Semiconductor Architecture Development 1.20.2 RISC-V-Based Processor Design Opportunities 1.20.3 AI Accelerator and Domain-Specific Architecture Development 1.20.4 Edge AI and Embedded Processing IP Demand 1.20.5 High-Performance Computing and Data Center Chip Design 1.20.6 Automotive Semiconductor Architecture and Software-Defined Vehicles 1.20.7 IoT and Connected Device Chip Design Requirements 1.21 Regional Semiconductor Chip Design Ecosystem Development and Investment 1.21.1 North American Semiconductor IP and Chip Design Ecosystem 1.21.2 European Semiconductor Design and IP Development Landscape 1.21.3 Asia Pacific Semiconductor Design and IP Demand Growth 1.21.4 China Semiconductor IP Development and Localization Strategies 1.21.5 India Semiconductor Chip Design and IP Ecosystem Development 1.21.6 Taiwan Semiconductor Design and Foundry Ecosystem 1.21.7 South Korea Semiconductor Design and Memory IP Development 1.21.8 Middle East Emerging Semiconductor Design Investments 1.22 Semiconductor Intellectual Property Market: Market Size and Forecast by Segmentation (by Value USD Million & Volume in Metric Tons) (2025–2034) 1.22.1 Semiconductor Intellectual Property Market Size and Forecast, By IP Type 1.22.1.1 Processor IP 1.22.1.2 CPU IP 1.22.1.3 GPU IP 1.22.1.4 DSP IP 1.22.1.5 AI/NPU IP 1.22.1.6 Microcontroller IP 1.22.1.7 Memory IP 1.22.1.8 Interface IP 1.22.1.9 Analog & Mixed-Signal IP 1.22.1.10 Security IP 1.22.1.11 Others 1.22.2 Semiconductor Intellectual Property Market Size and Forecast, By IP Core Type 1.22.2.1 Soft IP Core 1.22.2.2 Firm IP Core 1.22.2.3 Hard IP Core 1.22.3 Semiconductor Intellectual Property Market Size and Forecast, By Revenue Model 1.22.3.1 License Revenue 1.22.3.2 Royalty Revenue 1.22.3.3 Services & Support Revenue 1.22.4 Semiconductor Intellectual Property Market Size and Forecast, By Semiconductor Device Type 1.22.4.1 Microprocessors 1.22.4.2 Microcontrollers 1.22.4.3 GPUs & Graphics Processors 1.22.4.4 AI Accelerators / NPUs 1.22.4.5 Connectivity & Networking ICs 1.22.4.6 Application-Specific ICs 1.22.4.7 Programmable Logic Devices 1.22.4.8 Others 1.22.5 Semiconductor Intellectual Property Market Size and Forecast, By Customer Type 1.22.5.1 Fabless Semiconductor Companies 1.22.5.2 Integrated Device Manufacturers 1.22.5.3 Foundries 1.22.5.4 Others 1.22.6 Semiconductor Intellectual Property Market Size and Forecast, By End-Use Industry 1.22.6.1 Consumer Electronics 1.22.6.2 Automotive 1.22.6.3 Telecommunications 1.22.6.4 Data Centers & Cloud Computing 1.22.6.5 Industrial 1.22.6.6 Healthcare 1.22.6.7 Aerospace & Defense 1.22.6.8 Others 1.22.7 Semiconductor Intellectual Property Market Size and Forecast, By Region 1.22.7.1 North America 1.22.7.1.1 United States 1.22.7.1.2 Canada 1.22.7.1.3 Mexico 1.22.7.2 Europe 1.22.7.2.1 United Kingdom 1.22.7.2.2 France 1.22.7.2.3 Germany 1.22.7.2.4 Italy 1.22.7.2.5 Switzerland 1.22.7.2.6 Spain 1.22.7.2.7 Sweden 1.22.7.2.8 Russia 1.22.7.2.9 Rest of Europe 1.22.7.3 Asia Pacific 1.22.7.3.1 China 1.22.7.3.2 South Korea 1.22.7.3.3 Japan 1.22.7.3.4 India 1.22.7.3.5 Australia 1.22.7.3.6 Indonesia 1.22.7.3.7 Philippines 1.22.7.3.8 Malaysia 1.22.7.3.9 Vietnam 1.22.7.3.10 Thailand 1.22.7.3.11 Rest of Asia Pacific 1.22.7.4 Middle East And Africa 1.22.7.4.1 South Africa 1.22.7.4.2 Turkey 1.22.7.4.3 Saudi Arabia 1.22.7.4.4 UAE 1.22.7.4.5 Qatar 1.22.7.4.6 Egypt 1.22.7.4.7 Nigeria 1.22.7.4.8 Rest of ME&A 1.22.7.5 South America 1.22.7.5.1 Brazil 1.22.7.5.2 Argentina 1.22.7.5.3 Chile 1.22.7.5.4 Colombia 1.22.7.5.5 Rest Of South America 2. SECTION B – COMPETITIVE INTELLIGENCE & INDUSTRIAL ECOSYSTEM 2.1 Competitive Landscape 2.1.1 MMR Competition Matrix 2.1.2 Competitive Positioning of Leading Key Players [Revenue and Market Share (%)] 2.1.3 Key Players Benchmarking 2.1.4 Company Name 2.1.5 Headquarter 2.1.6 Product Portfolio 2.1.7 Product Quality & Reliability 2.1.8 Technology Innovation & Differentiation 2.1.9 Advanced-Node IP Capability 2.1.10 Chip Design Ecosystem Integration 2.1.11 EDA Integration 2.1.12 Customer Base 2.1.13 End-Use Industry Coverage 2.1.14 Revenue (2025) 2.1.15 R&D Investment (%) 2.1.16 Profit Margin (%) 2.1.17 Growth Rate (Y-o-Y %) 2.1.18 Geographic Presence 2.1.19 Market Structure 2.1.19.1 Market Leaders 2.1.19.2 Market Followers 2.1.19.3 Emerging Players 2.1.20 Growth Rate/Y-o-Y (%) of Companies 2.1.21 Profit Margin (%) of Companies 2.1.22 R&D Investments (%) of Companies 2.1.23 Mergers and Acquisitions Details 2.1.24 Recent Key Developments 2.2 Competitive Landscape and Industry Structure Analysis 2.2.1 Market Concentration Levels and Competitive Intensity Across Semiconductor IP Industry 2.2.2 Competitive Positioning Strategies Among Leading Semiconductor IP Providers 2.2.3 Entry Barriers and Challenges for New IP Participants 2.2.4 Technology Leadership Influence on Competitive Market Positioning 2.2.5 Market Share Distribution Patterns Among Established and Emerging IP Providers 2.2.6 Competitive Benchmarking Based on IP Performance, Licensing, Verification, and Integration 2.3 Company Market Share and Positioning Analysis (2024–2025) 2.3.1 Revenue-Based Market Share Comparison Across Leading Semiconductor IP Companies 2.3.2 Market Positioning Across Processor, Interface, Memory, Security, and Physical IP 2.3.3 Growth Performance Analysis of Emerging IP Providers 2.3.4 Competitive Licensing Benchmarking Across Major Industry Participants 2.3.5 Impact of Architecture Leadership on Market Share Expansion 2.3.6 IP Portfolio Breadth and Technology Differentiation 2.4 Strategic Initiatives and Expansion Strategy Analysis 2.4.1 Mergers and Acquisitions Shaping Semiconductor IP Competitive Landscape 2.4.2 Expansion of IP Portfolios Across Advanced Chip Design Applications 2.4.3 Global Market Entry and Expansion Strategies Among Leading IP Providers 2.4.4 Strategic Partnerships Strengthening Chip Designer Relationships 2.4.5 Investment in AI, Chiplet, and Advanced Architecture Technologies 2.4.6 RISC-V Ecosystem Development and Open-Architecture Strategies 2.4.7 Foundry and EDA Ecosystem Partnerships 2.5 Financial Performance and Profitability Benchmarking 2.5.1 Revenue Growth Trends Across Leading Semiconductor IP Providers 2.5.2 Profit Margin Analysis and Cost Structure Comparison 2.5.3 Investment Trends in Research and Development Activities 2.5.4 Financial Resilience During Semiconductor Industry Cycles 2.5.5 Impact of Licensing Revenue on Overall Company Profitability 2.5.6 Recurring Revenue Contribution to Business Performance 2.5.7 IP Portfolio Expansion and Revenue Diversification 2.6 Chip Designer and IP Developer Engagement Analysis 2.6.1 Fabless Semiconductor Company Relationships With Leading IP Developers 2.6.2 IDM and Foundry Engagement With IP Developers 2.6.3 Long-Term IP Licensing Agreement Structures 2.6.4 Customer Retention and IP Developer Ecosystem Lock-In Strategies 2.6.5 Technical Support and IP Integration Services 2.6.6 Co-Development and Custom IP Design Models 2.6.7 Design-Win and Customer Pipeline Analysis 2.7 Semiconductor IP Developer Innovation Leadership and R&D Investment Analysis 2.7.1 Research and Development Investment Trends Across Leading IP Developers 2.7.2 Innovation Leadership Among Semiconductor IP Developers 2.7.3 Advanced Processor and Accelerator IP Development Strategies 2.7.4 AI and Machine Learning IP Development Investments 2.7.5 Chiplet and Advanced Packaging IP Development 2.7.6 RISC-V and Open-Source Hardware Innovation 2.7.7 Security and Functional Safety IP Development 2.8 Company Profile: 30+ Key Players 2.8.1 Detailed Profile Parameters 2.8.1.1 Overview 2.8.1.2 Business Portfolio 2.8.1.3 Financial Overview 2.8.1.4 SWOT Analysis 2.8.1.5 Strategic Analysis 2.8.1.6 Recent Developments 2.8.2 North America 2.8.2.1 Synopsys, Inc. 2.8.2.2 Cadence Design Systems, Inc. 2.8.2.3 Rambus Inc. 2.8.2.4 CEVA, Inc. 2.8.2.5 Lattice Semiconductor Corporation 2.8.2.6 Silicon Image (Lattice Semiconductor Corporation — acquired 2015) 2.8.2.7 Silicon Storage Technology, Inc. (Microchip Technology Inc.) 2.8.2.8 Microchip Technology Inc. 2.8.2.9 Achronix Semiconductor Corporation 2.8.2.10 Analog Bits, Inc. 2.8.2.11 Arteris, Inc. 2.8.2.12 Eureka Technology, Inc. 2.8.2.13 Open Five, Inc. 2.8.2.14 Silvaco, Inc. 2.8.2.15 CAST, Inc. 2.8.2.16 Avery Design Systems, Inc. 2.8.2.17 Nvidia Corporation 2.8.2.18 Qualcomm Incorporated 2.8.2.19 Intel Corporation 2.8.2.20 Altera Corporation (Silver Lake / Intel Corporation — majority stake since 2025 spin-off) 2.8.2.21 Advanced Micro Devices, Inc. (AMD) 2.8.2.22 Xilinx, Inc. (Advanced Micro Devices, Inc. — acquired 2022) 2.8.2.23 Siemens EDA (Siemens AG — formerly Mentor Graphics, acquired 2017) 2.8.2.24 Broadcom Inc. 2.8.2.25 SiFive, Inc. 2.8.2.26 Others 2.8.3 Europe 2.8.3.1 Arm Holdings plc (SoftBank Group Corp. — majority shareholder) 2.8.3.2 Imagination Technologies Group plc (Canyon Bridge Capital Partners) 2.8.3.3 Alphawave IP Group plc (Alphawave Semi) 2.8.3.4 Cobham Gaisler AB (Cobham Limited) 2.8.3.5 Dolphin Design SAS 2.8.3.6 Dream Chip Technologies GmbH 2.8.3.7 TES Electronic Solutions GmbH 2.8.3.8 TransPacket AS 2.8.3.9 Others 2.8.4 Asia Pacific 2.8.4.1 eMemory Technology, Inc. 2.8.4.2 VeriSilicon Microelectronics Co., Ltd. (VeriSilicon Holdings Co., Ltd.) 2.8.4.3 Faraday Technology Corporation 2.8.4.4 M31 Technology Corporation 2.8.4.5 Andes Technology Corporation 2.8.4.6 Renesas Electronics Corporation 2.8.4.7 Fujitsu Limited 2.8.4.8 Digital Media Professionals Inc. (DMP) 2.8.4.9 TAKUMI Corporation 2.8.4.10 Others 3. SECTION C – KEY INSIGHTS, STRATEGIC OUTLOOK & METHODOLOGICAL FRAMEWORK 3.1 Key Findings 3.2 Strategic Moves & Industry Outlook 3.3 Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements